Arrears or advance stage payments
| Arrears | Advance | |
|---|---|---|
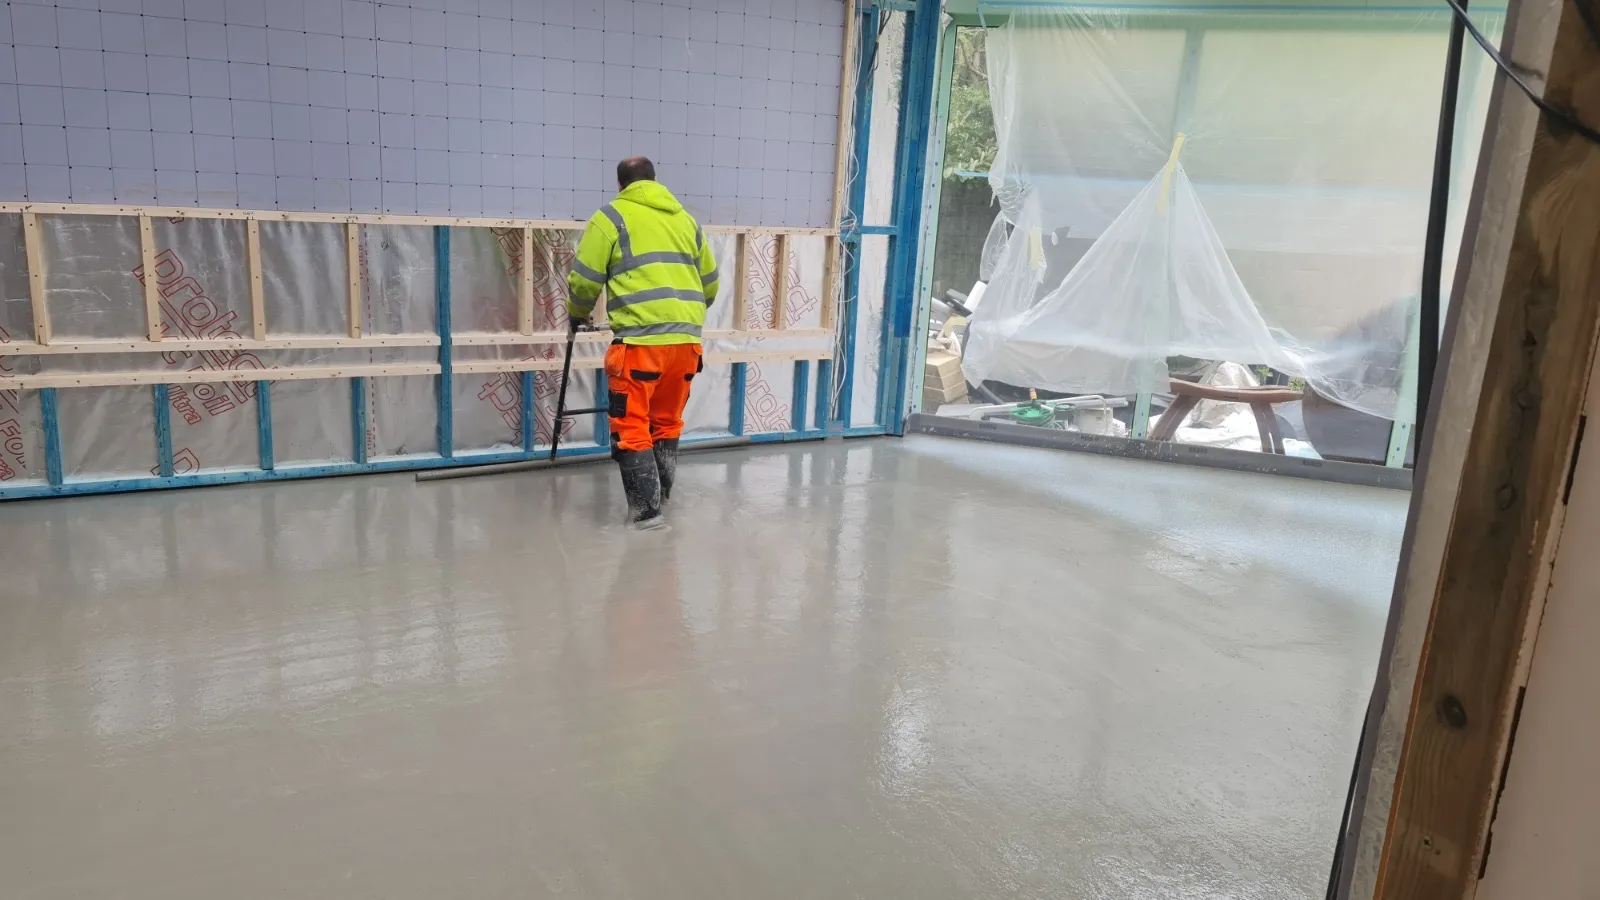
| How it works | Money is released after each stage is built and valued | Money is released at the start of each stage |
| Cash you need | You fund each stage first, then you're reimbursed | Much less of your own cash tied up |
| Rates | Usually lower | Usually a little higher |
| Suits | Self-builders with good cash reserves | Self-builders with limited cash reserves |
Who lends on self-build
Self-build lending in Scotland comes mainly from building societies and specialist lenders, with some products accessed through self-build specialists such as BuildStore. Which lenders are active, and on what terms, changes often.
This guide is general information, not regulated mortgage or financial advice. Lender names and product features are described as at October 2026 and change often, so take advice from an FCA-authorised mortgage adviser before committing.
General mortgage brokers rarely deal with self-build. A broker who specialises in it will understand stage releases, valuations and which lenders currently suit your project.
What lenders look at
- Affordability, based on the total borrowing for the land and the build.
- Your professional team, and who will oversee the work.
- Planning permission, usually needed before construction funds are released.
- The Building Warrant, usually needed before construction drawdowns.
- A structural warranty or, with some lenders, a professional consultant's certificate.
Timing in Scotland
You are legally committed once missives are concluded, with no cooling-off period. Have an agreement in principle before you make an offer on a plot.
Questions
Can I get a mortgage to build a house in Scotland?
Yes. Self-build mortgages release money in stages as the house is built, either after each stage (arrears) or at the start of it (advance).
Do I need planning permission before getting a self-build mortgage?
You can usually get an agreement in principle before, but most lenders need planning permission and a Building Warrant before releasing money for construction.
General guidance for Scotland, not legal, tax, financial or planning advice for your project. Rules change, so check current official guidance and take advice specific to your site before acting.